Three finance strategies for purchasing your next property
Whether you’re upsizing, downsizing or just moving to a house in a new location, your situation has probably changed…


Buying your first home can feel like a race against time. In recent years, rising property prices, strong buyer demand and fierce competition have made it challenging for many Australians to get a foot on the property ladder.
But the market is changing and that could create new opportunities for first-home buyers.
With properties taking longer to sell and competition easing in some areas, buyers may have more time to compare their options, do their research and make informed decisions without feeling pressured to rush into a purchase.
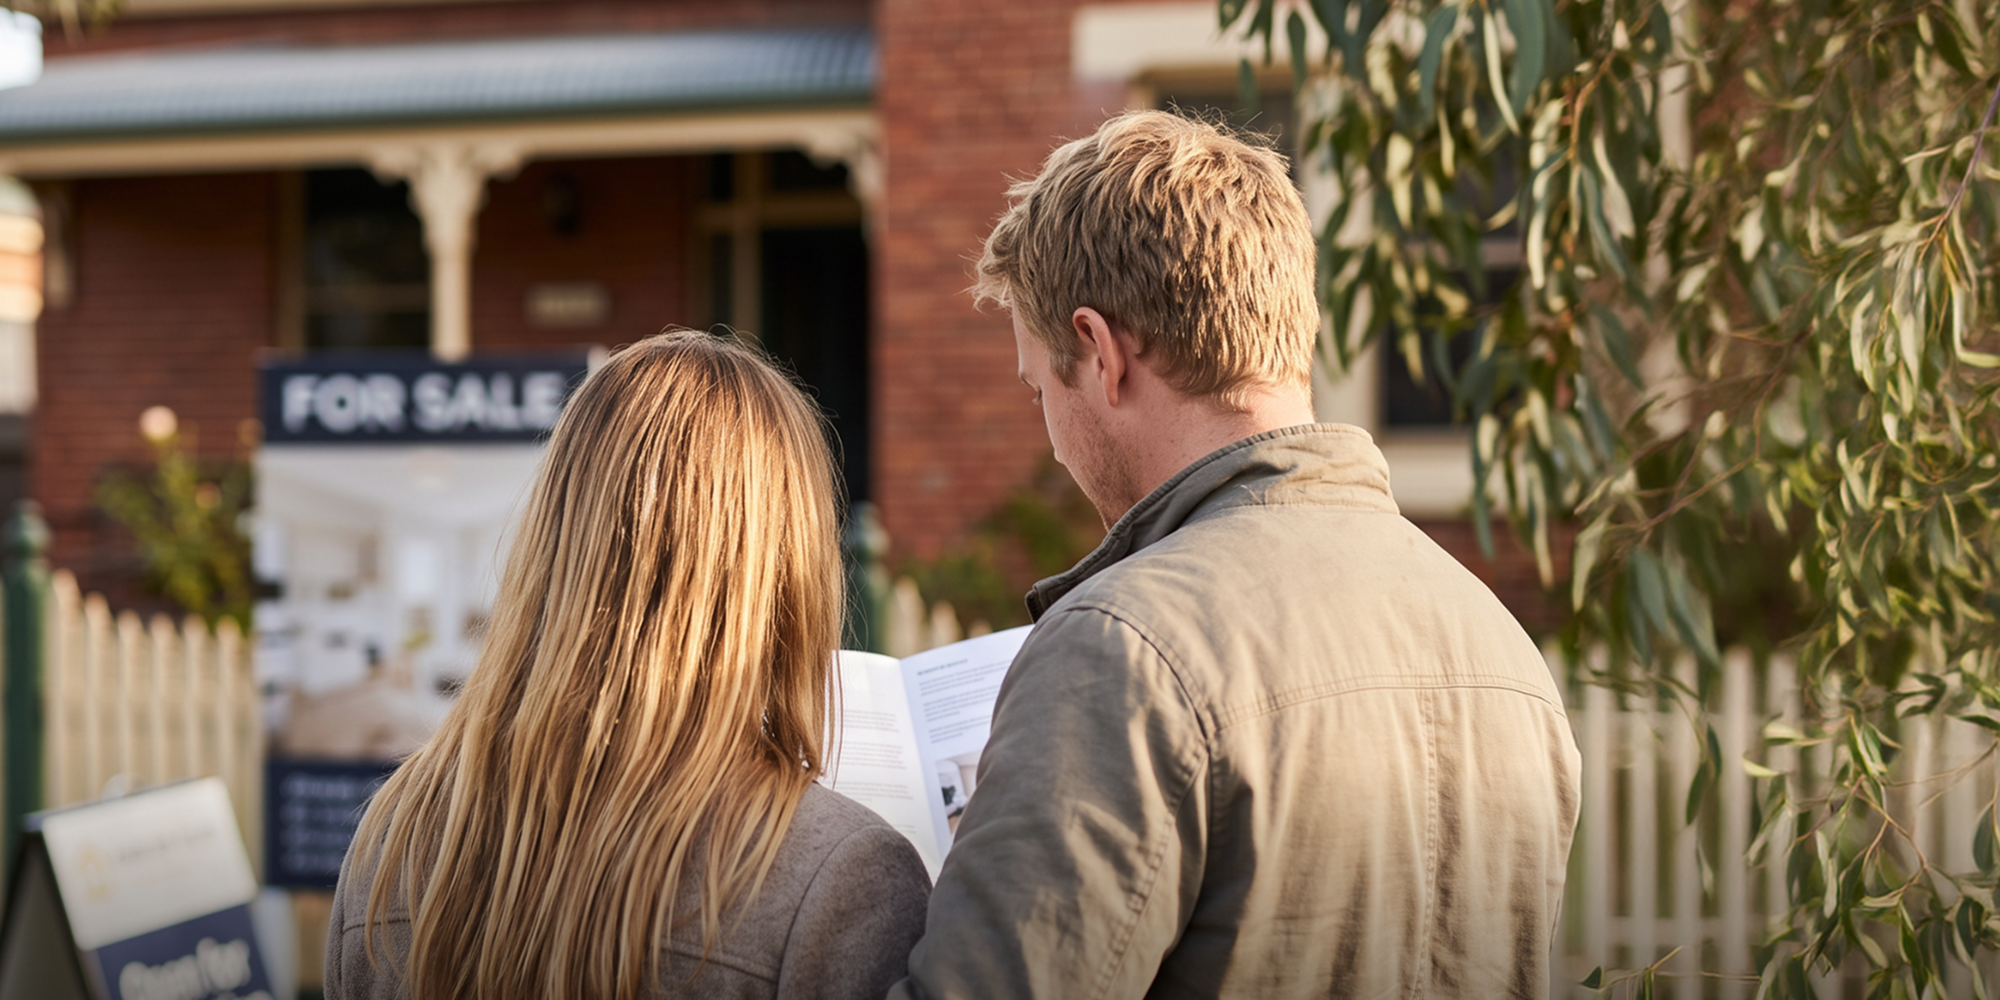
While affordability and higher interest rates remain challenges, a slower market could offer advantages for buyers who are financially prepared and understand their borrowing options.
If buying your first home is on your radar, here’s how current market conditions could influence your plans.
Entering the property market remains a priority for many Australians, but higher borrowing costs and ongoing affordability pressures are encouraging buyers to be more considered before making a commitment.
Recent data showed mortgage demand among first-home buyers fell by 20.1% nationally compared with a year earlier. At the same time, the average first-home buyer loan size reached a record $740,000.
Interest rates are also an important consideration. Following the Reserve Bank of Australia’s latest cash rate increase to 4.6% in September, many lenders adjusted their variable home loan rates, adding further pressure to household budgets.
Although these conditions present challenges, a slowdown in buyer activity can have a potential upside. With fewer buyers competing for properties in some areas, financially prepared purchasers may have more time to research the market, assess their options and negotiate with sellers.
There may also be government support available to help eligible buyers enter the market. For example, the Australian Government 5% Deposit Scheme allows eligible first-home buyers to purchase a home with a deposit as low as 5%, without paying Lenders Mortgage Insurance (LMI), subject to the scheme’s eligibility requirements.
With the next RBA cash rate decision scheduled for November, uncertainty around interest rates remains. Rather than relying on a particular rate outcome, prospective buyers can benefit from understanding what they can comfortably afford under different lending scenarios.
For those who have been waiting for a less competitive market, current conditions could be worth exploring. The key is to understand your financial position before deciding whether the timing is right.
Competition from property investors has been another hurdle for first-home buyers, particularly in areas where affordable properties attract strong demand.
Recent lending figures suggest investor activity has started to cool. New investor loan commitments fell by 8.6% in the June quarter, marking their steepest quarterly decline in almost four years. By comparison, approved first-home buyer loans fell by 2.9% over the same period.
While these figures don’t guarantee less competition in every suburb or price range, a reduction in investor activity could give some first-home buyers more room to manoeuvre.
Depending on the local market, this may translate into a wider selection of properties, fewer competing offers and more opportunities to negotiate on price or conditions.
For buyers who previously found themselves competing against multiple interested purchasers, a more balanced market could make the search for a first home feel more manageable.
Property market conditions vary across Australia, but recent data has pointed to softer housing values in several markets. National housing values declined by 1.1% in September, with Brisbane recording the largest monthly fall among the capital cities.
Housing turnover has also slowed, with properties generally taking longer to sell. Although the number of new listings remains an important factor, longer selling times can contribute to a greater pool of properties available for buyers to consider.
This can create a different buying experience compared with the fast-moving conditions of recent years.
Rather than feeling pressured to make an immediate offer, buyers may have more time to inspect properties, compare locations, review their finances and decide whether a home suits their needs and budget.
In some circumstances, sellers may also be more open to negotiations when a property has been on the market for longer.
Of course, opportunities will depend on the location, property type and level of demand. Popular suburbs and well-priced homes can still attract considerable interest.
The important thing is to understand the market you’re buying into and have your finance organised so you can act when the right opportunity comes along.
Higher interest rates have affected borrowing capacity and increased repayments for many prospective homeowners. For buyers already working with a tight budget, even a small change in lending conditions can influence the type of property they can afford.
As a general guide, a one percentage point increase in mortgage rates can reduce maximum borrowing capacity by around 10%, although the actual impact depends on your income, living expenses, existing debts and the lender’s assessment criteria.
However, borrowing capacity isn’t the only factor to consider when buying a home.
A slower market may offer advantages through softer prices in some areas, less competition and more opportunities to negotiate. These conditions could help prepared buyers make more considered decisions rather than feeling pressured to stretch their budgets to secure a property.
The best approach is to understand your borrowing capacity, account for upfront costs and ongoing repayments and establish a budget that remains comfortable even if circumstances change.
It’s also worth investigating available first-home buyer incentives and deposit schemes to see whether you qualify for support that could make purchasing more achievable.
Ultimately, buying your first home isn’t just about securing the largest loan possible. It’s about finding a property that suits your needs and budget while ensuring the financial commitment is sustainable over the long term.
A changing property market can create opportunities, but knowing when and how to act starts with having the right finance strategy.
At 1st Street, we can help you understand your borrowing capacity, explore suitable home loan options and identify government incentives that may be available to you as a first-home buyer.
Whether you’re just starting to save for a deposit or getting ready to make an offer, having a clear picture of your finances can help you move forward with greater confidence.
Take the first step towards your first home. Speak to our team today to discuss your home loan options and find out how we can help you prepare for your property purchase.
Whether you’re upsizing, downsizing or just moving to a house in a new location, your situation has probably changed…

Spring has arrived, bringing a renewed sense of excitement in the property market. Whether you’re…
Yes, that’s right. You pay zero, zip, nada.
1st Street’s premium service comes at no cost to you! 1st Street is paid by the lender when your loan settles, however, this will not affect your interest rate or loan fees! It is often more cost-effective for a mortgage broker to process a loan rather than the lenders processing it themselves in-house. In fact, we often find that we can save you money by negotiating on your behalf.
I want to buyI want to refinance
*While our core residential home loan services are provided free of charge, there may be instances where specific services require a fee. If you have any questions about which services are complimentary and which might incur a charge, please feel free to reach out.


Use our online calculators to work out how much you can borrow, loan repayments, stamp duty and lots more.